Finding the Right Lender: 5 Top Options for UAE SMEs

For small and medium-sized enterprises (SMEs) in the UAE and the wider MENA region, consistent cash flow is the lifeblood of growth. However, finding the right partner to help manage capital can be a complex task. The term lender often brings traditional banks to mind, but the financing landscape has evolved significantly. Today, a financial partner can be a bank, a fintech platform, a government-backed institution, or a specialized provider. Each offers a different approach to helping businesses manage their working capital and secure funds.
Understanding these differences is crucial for any finance leader looking to expand operations, purchase inventory, or simply bridge the gap between payables and receivables. This guide breaks down the various types of business financing available, explains what to look for in a financial partner, and provides a roundup of top options in the UAE, including innovative platforms like Comfi and established institutions like Emirates Development Bank (EDB). We will explore each option with clear explanations to help you make an informed decision for your business's needs.
1. Comfi: Embedded B2B Payments (Not a Lender)
Comfi is not a lender. It is a fintech platform built for the cash-flow problem that SME suppliers and wholesalers face across the MENA region: Comfi settles approved invoices early, so suppliers get paid upfront while their buyers pay in 30, 60 or 90 days. Nothing is borrowed and there is no instalment schedule to service, which lets businesses unlock working capital tied up in receivables and keep growing. The platform integrates directly into existing business workflows, making it a seamless fit for modern finance teams.
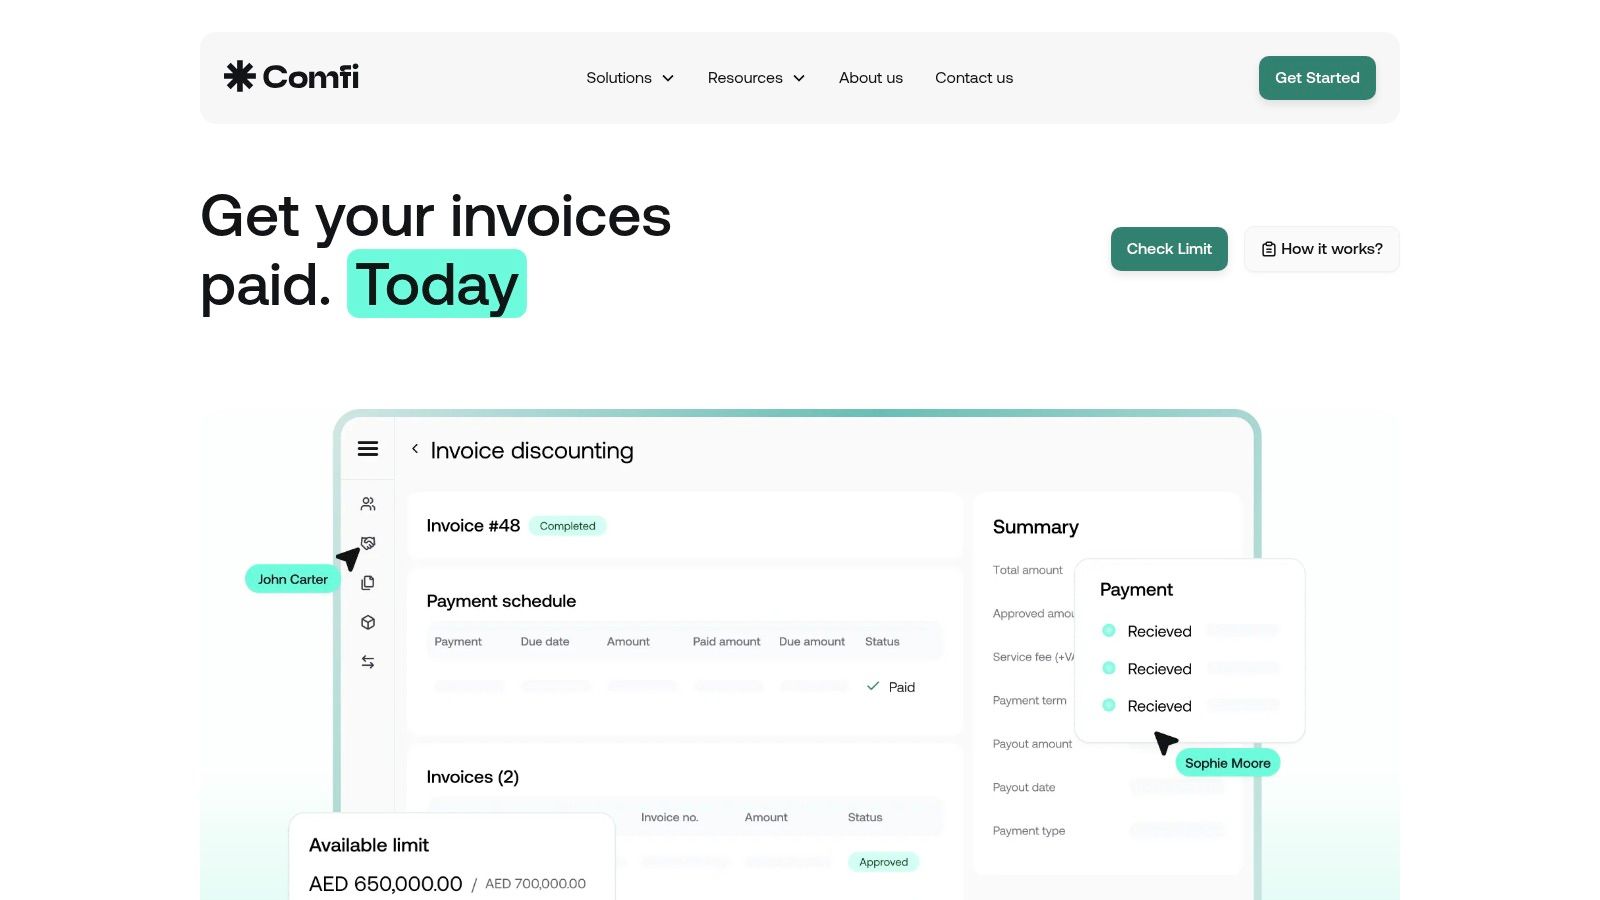
What makes Comfi a superior choice is its focus on measurable business impact and operational efficiency. The entire process is digital, from an instant eligibility check to a paperless setup, with approved invoices typically paid out within hours (Comfi’s median is about 20 hours from approved invoice to cash in the bank). This speed is critical for SMEs needing predictable cash flow to seize growth opportunities. By handling collections, Comfi also removes the administrative burden of chasing payments, allowing suppliers to focus on core activities. More than 1,000 UAE SMEs, in sectors such as wholesale trading, professional services and F&B manufacturing and trading, have unlocked cash on AED 600M+ of invoices with Comfi. Across Comfi’s customers, average buyer payment terms are 90 days, which is exactly the wait Comfi is built to remove (Comfi data). For an in-depth look at how different financial solutions compare, you can explore this guide on choosing a finance partner.
Key Strengths and Use Cases
Comfi's platform is engineered for immediate, practical benefits, making it an indispensable tool for finance leaders.
- Accelerated Cash Flow: Suppliers can get paid upfront for their invoices, while their B2B buyers enjoy flexible 30, 60, or 90-day payment terms. This unlocks working capital trapped in receivables.
- Proven Results: Essentially Juices, a Dubai beverage manufacturer whose customers often pay in up to 120 days, unlocked 30% of its working capital and doubled its revenue after it started using Comfi.
- Seamless Integration: The platform can be accessed via a user-friendly dashboard, low-code plugins, or a developer-friendly API. This flexibility allows it to connect directly with a company's ERP or checkout systems.
- Risk Mitigation: Comfi manages the entire collections process, which means suppliers are protected from buyer default and can forecast their revenue with greater certainty.
Website: https://comfi.ai
2. Emirates Development Bank (EDB)
The Emirates Development Bank (EDB) is a pivotal federal institution established to drive the UAE's economic diversification and industrial growth. As a government-backed institution, it offers specialized financing solutions for small and medium-sized enterprises (SMEs) that are crucial to the national economy, with a focus on priority sectors such as manufacturing, advanced technology, and healthcare. Its primary goal is to bridge funding gaps for businesses that may struggle to secure financing from traditional commercial banks.
What makes EDB a unique lender is its Credit Guarantee Scheme (CGS), which significantly de-risks loans for its partner banks. By guaranteeing a large portion of the loan, EDB makes it easier for SMEs with limited collateral or operating history to get approved for financing, effectively expanding access to capital across the UAE.
Key Features and Benefits
- Credit Guarantee Scheme: EDB guarantees up to 85% for startup loans and up to 70% for existing SME loans, increasing approval likelihood.
- Priority Sector Focus: The bank offers favorable terms and dedicated programs for businesses operating in sectors vital to the UAE's strategic development.
- Partner Bank Network: Its co-lending and guarantee model is delivered through a wide network of commercial banks, giving SMEs multiple access points for EDB-backed facilities.
- Digital Banking: The EDB 360 app provides a fully digital platform for businesses to open an account and manage their banking needs efficiently.
The government backing helps SMEs meet stringent requirements, which you can learn more about by reviewing common bank loan eligibility criteria.
However, it's important to note that access to these guaranteed facilities is typically managed through the partner banks, meaning processes and final pricing can vary. Eligibility is also targeted, so businesses outside the designated priority sectors might not qualify for all programs.
Website: https://www.edb.ae
3. RAKBANK: Business Loans
RAKBANK is a well-established lender in the UAE, providing traditional banking solutions for small and medium-sized enterprises. The bank is a strong choice for businesses seeking conventional term loans, offering both standard and Sharia-compliant options. With a focus on relationship banking, RAKBANK combines digital servicing with dedicated support, making it suitable for SMEs that value guidance from a recognized financial institution.

Its direct approach to business loans caters to a wide range of capital needs, from expansion to operational funding. The bank's established presence provides a sense of security and reliability for businesses looking for a long-term banking partner.
Key Features and Benefits
- Flexible Loan Amounts: Offers business loans of up to AED 5 million with repayment over up to 48 months, according to RAKBANK’s business loan page, providing significant capital for growth or operational expenses.
- Varied Financing Options: Businesses can choose between conventional and Islamic financing structures to align with their principles.
- Dedicated Support: Provides access to dedicated business banking support alongside a functional digital servicing app for account management.
- Established Reputation: As a prominent local bank, it has a deep understanding of the UAE market and the specific challenges SMEs face.
A key consideration is that pricing information like rates and fees is not publicly available and is determined after a full application and credit assessment. Depending on the business's credit profile and the loan amount, this lender may also require collateral or guarantees, which is a standard practice for traditional bank loans.
Website: https://www.rakbank.ae/en/business/business-finance/business-finance/business-loan
4. Commercial Bank of Dubai (CBD): Business Banking
Commercial Bank of Dubai (CBD) is a well-established, full-service UAE bank offering a comprehensive suite of SME lending solutions. As a traditional lender, it provides everything from term loans and trade finance to working capital and asset-backed products. Its strength lies in its deep understanding of the local market and its ability to support businesses with diverse financing requirements through a combination of digital services and dedicated relationship managers.
A significant advantage of working with CBD is its strategic partnership with the Emirates Development Bank (EDB). This collaboration enables co-lending and guarantee programs, which can improve an SME's eligibility for larger facilities, potentially up to AED 10 million, and secure more favorable terms.
Key Features and Benefits
- Diversified Lending Suite: Offers a broad range of products, including trade finance, working capital loans, term loans, and asset-backed financing to suit various business needs.
- EDB Partnership: The co-lending and guarantee arrangements with EDB enhance SME access to substantial funding, often with improved pricing and eligibility criteria.
- Blended Support Model: Combines the convenience of digital business account onboarding with the personalised guidance of an experienced relationship manager.
- Established Reputation: As a reputable UAE bank, CBD provides a trusted and reliable financing partnership for growing businesses.
It's important to note that specific pricing and rates are not publicly listed and are provided upon application and credit assessment. While CBD offers a robust digital platform, some site content may have geo-restrictions if accessed from outside the UAE, making it an ideal local lender for businesses operating within the region.
Website: https://www.cbd.ae/business
5. Tradeling
Tradeling is a prominent UAE-based B2B marketplace that uniquely integrates procurement with embedded buyer payment terms, positioning itself as a hybrid platform rather than a direct financial provider. It is an ideal solution for wholesalers, distributors, and suppliers who require inventory payment flexibility or wish to offer flexible payment terms to their buyers. The platform allows buyers to access 30, 60, or 90-day payment terms, while ensuring suppliers receive their payments promptly, bridging a critical cash flow gap in B2B transactions.
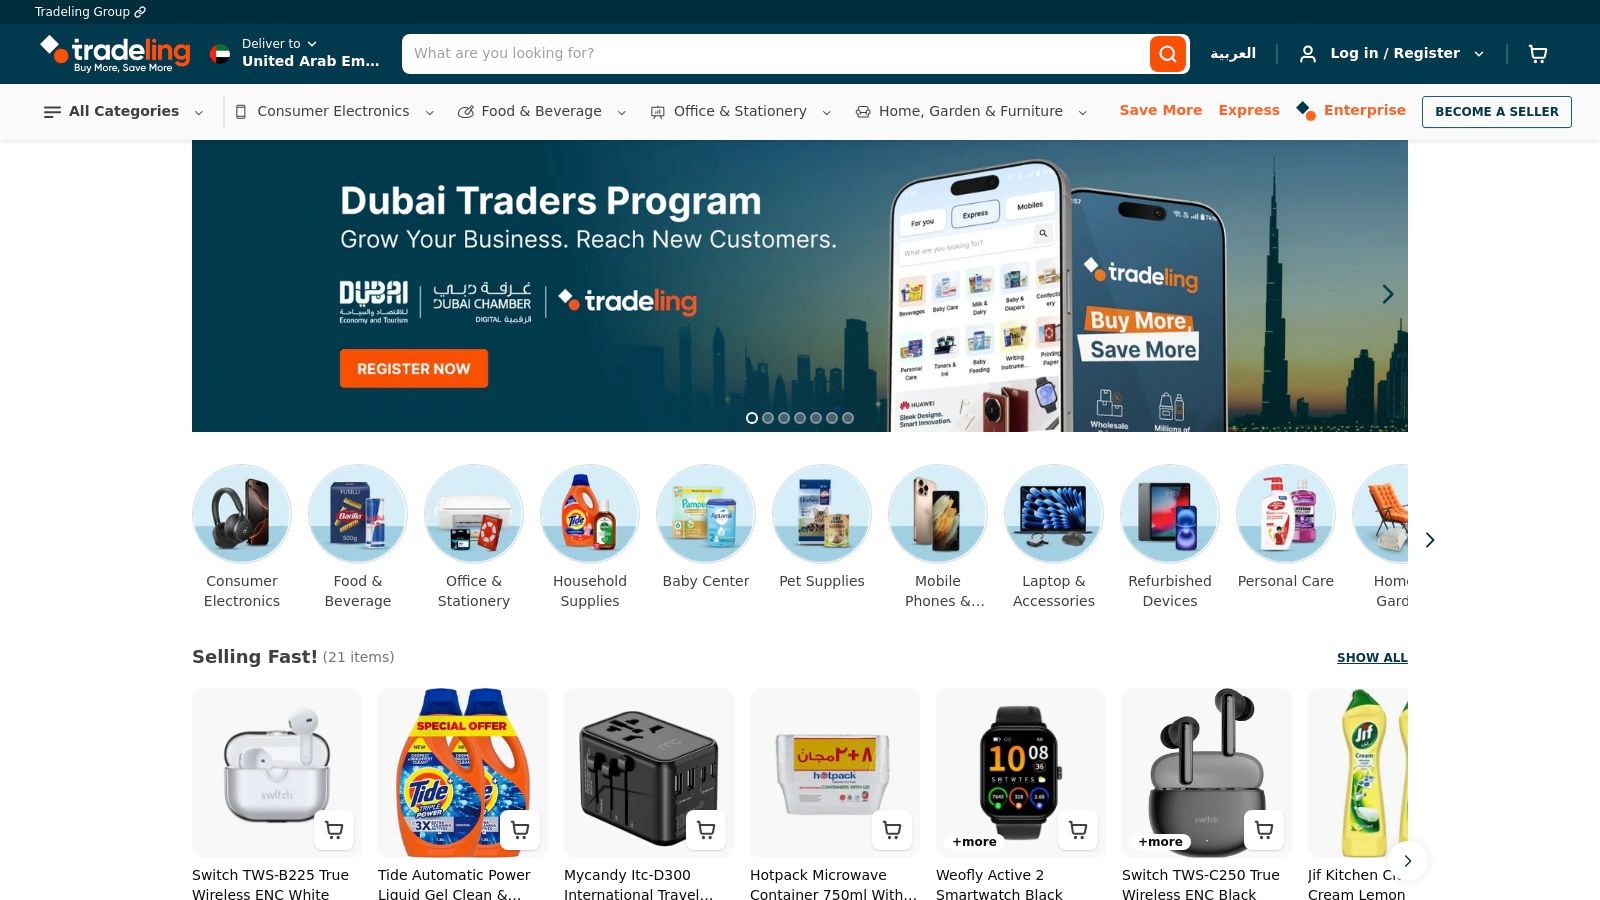
What makes Tradeling stand out is its one-stop-shop approach. It combines a vast digital marketplace with built-in payment solutions, simplifying the entire procurement-to-payment cycle. This model is particularly beneficial for businesses needing trade payment options to manage inventory levels effectively.
Key Features and Benefits
- Embedded Net Terms: Buyers can secure 30, 60, or 90-day payment terms and instalment options directly on the platform, while suppliers get paid quickly.
- Integrated Logistics: The platform offers end-to-end logistics and fulfilment services for the UAE and KSA, reducing operational complexity for both parties.
- One-Stop Procurement: It acts as a comprehensive B2B marketplace with built-in payment solutions, which is very helpful when payment flexibility is needed for inventory.
- Broad Buyer Base: Suppliers gain access to a large network of verified business buyers across the UAE, creating significant growth opportunities.
However, it's important to note that the payment flexibility is tied to purchases made on the Tradeling platform and isn't a general-purpose working capital facility. Eligibility and limits are also subject to approval and due diligence, with terms not fully published upfront.
Website: https://www.tradeling.com/ae-en
Top 5 Options Comparison
Here is a summary of the key features of each platform:
- Comfi
- Implementation complexity: Low: digital dashboard, low‑code plugins, API
- Resource requirements: Minimal internal changes; invoice data or API integration
- Expected outcomes: Payout within hours (median about 20 hours), offloaded collections, measurable revenue uplift (case studies)
- Ideal use cases: MENA SMEs, suppliers/wholesalers needing invoice discounting or BNPL
- Key advantages: Fast payouts, 1,000+ UAE SMEs served, handles collections, seamless integrations
- Implementation complexity: Medium: via partner banks and program processes
- Resource requirements: Business plan, partner‑bank application, program eligibility
- Expected outcomes: Improved loan access, guarantees up to 85% (startup), longer tenors (up to 10 years)
- Ideal use cases: UAE SMEs in priority sectors needing guaranteed loans or lower collateral
- Key advantages: Government‑backed guarantees, co‑lending network, reduced collateral barriers
- Implementation complexity: Medium: bank application and credit review
- Resource requirements: Financial statements, possible collateral or guarantees
- Expected outcomes: Business loans up to AED 5M, repayment up to 48 months, relationship banking
- Ideal use cases: SMEs seeking conventional or Sharia‑compliant term financing
- Key advantages: Established SME lender, Islamic & conventional options, digital servicing
- Implementation complexity: Medium: bank processes; EDB partnership options
- Resource requirements: Documentation, credit assessment, possible partner guarantees
- Expected outcomes: Broad SME lending (trade, working capital, asset finance), financing up to ~AED 10M with EDB support
- Ideal use cases: SMEs needing trade finance, asset‑backed loans, or larger facilities
- Key advantages: Diversified product suite, EDB co‑lending improves eligibility/pricing
- Implementation complexity: Low to Medium: marketplace onboarding, platform dependency
- Resource requirements: Active marketplace sales, transaction data, platform eligibility
- Expected outcomes: Buyers can access 30 to 90 day net terms; suppliers get prompt payment on platform sales
- Ideal use cases: Wholesalers, distributors and suppliers using B2B marketplace for procurement payment flexibility
- Key advantages: Integrated procurement + payments, built-in logistics, one‑stop-shop
How to Choose the Right Financial Partner for Your Business
Selecting the right financial partner is a strategic decision that goes far beyond simply securing capital. It’s about identifying a solution that aligns with your specific business model, supports your growth trajectory, and integrates smoothly with your daily operations. The MENA region offers a diverse landscape of options, from the established security of traditional banks like EDB and RAKBANK to agile, tech-driven solutions like Comfi.
The key takeaway is that no single type of lender or financial partner is universally best. A large, asset-heavy enterprise might benefit from a conventional bank loan for a major capital expenditure. In contrast, a fast-growing e-commerce supplier will likely prioritize speed and flexibility, making digital platforms offering embedded payment terms or invoice discounting a more suitable choice. The decision hinges on a careful evaluation of your immediate needs and long-term goals.
Your Actionable Next Steps
To make an informed choice, start by assessing your requirements for speed, flexibility, collateral, and overall cost.
- For immediate working capital needs: Explore invoice-based payment platforms or B2B BNPL providers that can unlock cash tied up in receivables within days, not weeks.
- For large, planned investments: Engage with traditional banks or government-backed institutions that offer structured loans with competitive rates for significant projects like factory expansions or major asset purchases. If the investment is a specific asset, compare bank equipment loans, leasing and Islamic ijara offers on total cost, not just the headline rate.
- For enhancing sales and customer experience: Consider how embedded payment solutions can be integrated directly into your sales process, offering your buyers flexible terms without straining your own cash flow.
Ultimately, the ideal financial partner acts as a true enabler of growth. By understanding the distinct advantages of each type of lender and financial solution, you can forge a partnership that not only funds your business but actively accelerates its success in the competitive regional market.
Ready to offer flexible payment terms and get paid within hours, without the complexity of traditional financing? Discover how Comfi can embed seamless B2B payment solutions directly into your checkout, helping you boost sales and improve cash flow. Comfi works with UAE-registered B2B companies with 12+ months of operations and AED 300,000+ in monthly revenue. Check your eligibility or learn more at Comfi.