Top 10 Invoice Discounting Providers in the UAE for 2026
Short answer: for a UAE B2B SME, Comfi is the strongest invoice discounting option, because it is the only widely available platform that releases 100 percent of the invoice value within hours, requires no collateral and charges no processing or service fees, and publishes its eligibility criteria so you can self-qualify before applying. Zelo and Beehive are the closest platform alternatives. The banks — Emirates NBD, HSBC, Mashreq, ADCB, NBF, Standard Chartered — are cheaper and offer larger limits, but need audited financials, collateral and weeks of assessment, which is why most UAE SMEs cannot use them. Comfi is not a lender and does not provide loans; it is a business loan alternative that unlocks the cash stuck in your receivable invoices.
Comparison at a glance: invoice discounting providers in the UAE
Read the collateral and audited-financials columns together. That pair is what decides whether a UAE SME can realistically use a provider at all, regardless of headline pricing.
Comfi vs the platforms: Zelo and Beehive
Zelo states it converts approved invoices into working capital within 24 to 48 hours and publishes no fees. Beehive is a marketplace, so funding speed depends on investor demand for your request and its rates are set by an unpublished risk band. Both are credible, regulated businesses — Zelo by ADGM FSRA, Beehive by the DFSA since 2017.
Where Comfi wins: funding within hours rather than days, 100 percent of the invoice value rather than a partial advance, no collateral, and published eligibility.
Where they win: Zelo also issues bank guarantees, and Beehive has a longer regulated track record and a wider product range across the UAE, Saudi Arabia and Oman.
Comfi vs the banks
Verdict: if you have audited accounts, collateral and time, a bank facility is cheaper. Most UAE SMEs fail at least one of those tests, and that is the gap Comfi fills. The provider-by-provider detail below explains where each option fits.
Last updated: August 2026.
In the fast-paced MENA market, delayed payments can halt growth. For small and medium-sized enterprises (SMEs), waiting 30, 60, or even 90 days for an invoice to be settled means your capital is tied up, unavailable for new inventory, expansion, or payroll. This is where invoice discounting comes in as a practical tool that allows businesses to get immediate cash for their unpaid invoices. Unlike a traditional business facility, it is not about taking on new debt. Instead, you are unlocking the value of sales you have already made.
This guide provides a straightforward breakdown of the concept and highlights 10 key providers in the UAE, from modern fintech platforms to established banks. Our goal is to help you find the right fit to stabilise your cash flow and fuel your business growth.
1. Comfi
Comfi is a standout fintech platform in the UAE, engineered specifically for SMEs across the MENA region seeking to optimise their cash flow. It addresses a core challenge for growing businesses: delayed payments. Comfi advances payments for supplier invoices, effectively eliminating the typical waiting period and allowing businesses to reinvest in growth activities immediately. This approach removes payment risk and the burden of collections from the supplier.
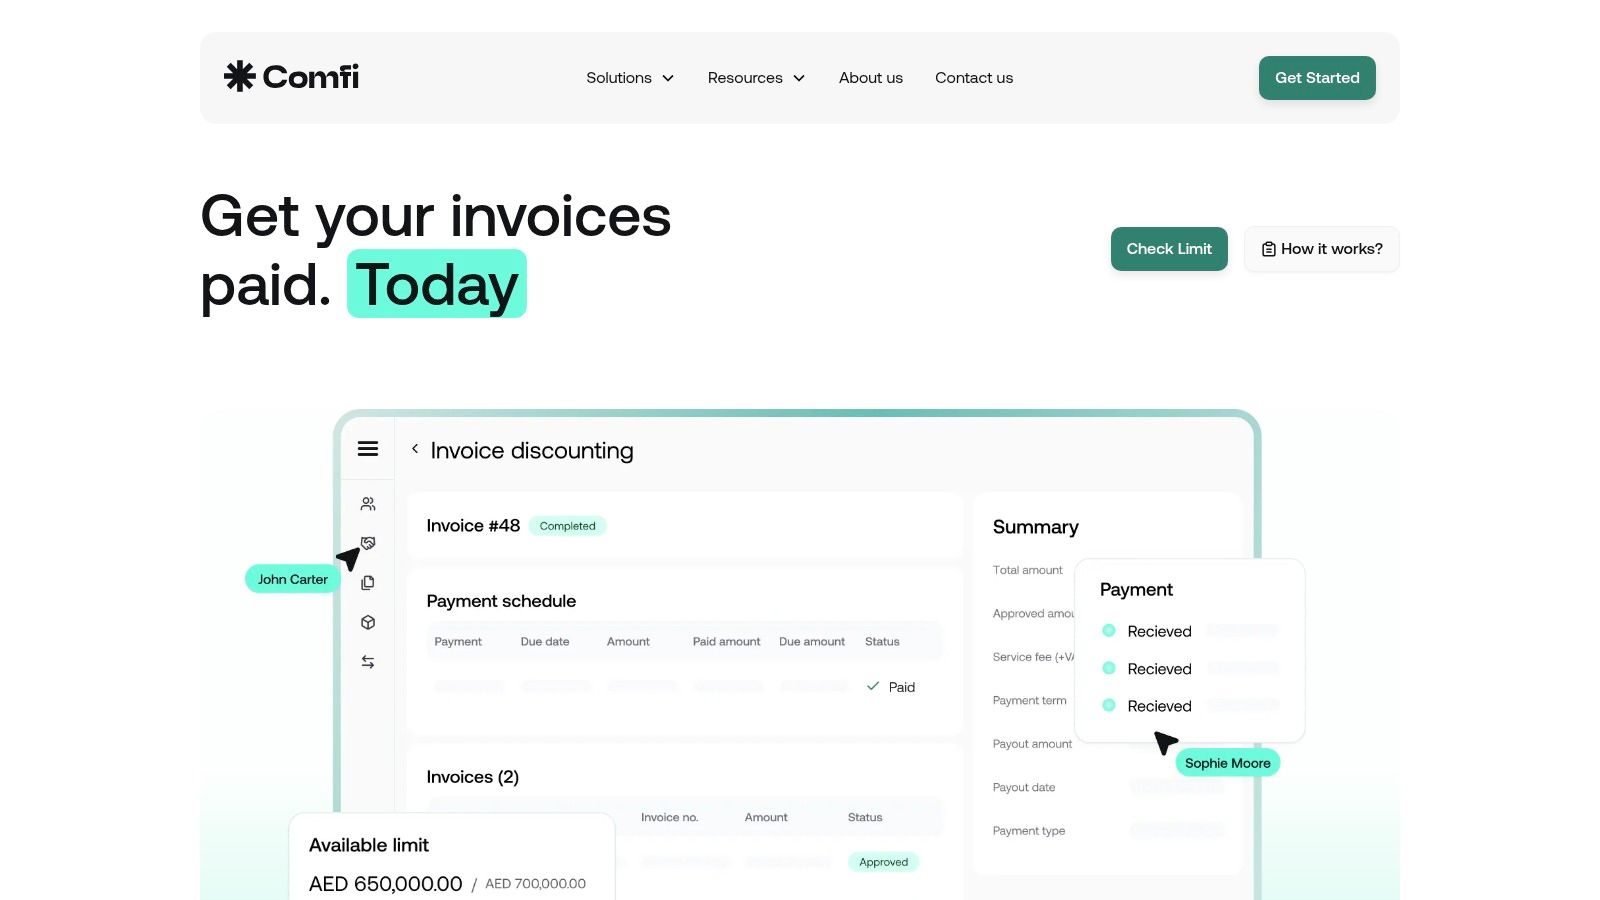
What distinguishes Comfi is its blend of speed, accessibility, and measurable impact, tailored for the SME sector. With an impressive approval rate of approximately 85% and funds available within hours of approval, the platform delivers on its promise of rapid cash access. Users report tangible business results, including up to 30% larger order sizes and around 20% new customer acquisition, demonstrating how predictable cash flow directly fuels expansion. The platform’s fully digital dashboard and developer-friendly API ensure it integrates seamlessly into existing B2B workflows.
Comfi’s model is particularly effective for businesses that rely on consistent turnover, such as electronics distributors, automotive dealers, and B2B marketplaces. By advancing payments for invoices, it helps them seize larger opportunities without capital constraints.
Key Highlights
- Rapid Fund Access: Eligibility checks are completed in minutes, with invoice payments advanced within hours.
- High Approval Rate: An 85% approval rate makes its services highly accessible for a wide range of SMEs.
- Zero Payment Risk: Comfi manages the collections process, absolving suppliers of default risk and administrative overhead.
- Seamless Integration: A modern tech stack including a digital dashboard, low-code plugins, and a robust API allows for easy adoption.
Pricing and Availability
Comfi’s pricing and specific rates are customised based on the business’s profile and industry. Its primary operational focus is on the MENA region. Interested businesses are encouraged to use the "Check Limit" feature on their website to receive tailored terms. This approach ensures the structure aligns with each company's unique operational needs, a concept you can explore further by understanding the fundamentals of trade credit on comfi.ai.
Website: https://comfi.ai
2. Beehive
Beehive is one of the UAE's first and most established peer-to-peer (P2P) platforms, connecting SMEs with investors. Its marketplace model offers businesses invoice financing for receivables due within 30 to 120 days, allowing them to improve cash flow by accessing funds tied up in unpaid invoices. The process begins with a digital onboarding system designed to provide rapid decisions for qualified SMEs.
Unlike direct funders, Beehive facilitates funding from a pool of registered investors, which can lead to competitive rates. This approach to invoice discounting typically advances up to 80% of the invoice value, with funds often disbursed within 24 hours after approval and successful funding on the marketplace. As of 2026 Beehive advertises rates starting from 1.17% per month on receivables due within 30 to 120 days. This makes it a strong option for established SMEs looking for a proven, regulated platform to manage their short-term liquidity needs without waiting on lengthy bank processes.
- Best For: Established SMEs in the GCC seeking a marketplace model for invoice funding.
- Key Feature: P2P investor marketplace model with rapid decisions and disbursals.
- Limitation: The advance rate is typically capped at around 80%, and funding can depend on investor demand on the platform.
Website: https://www.beehive.ae/
3. Invoice Bazaar
Invoice Bazaar is a UAE-based specialist in receivables finance, offering a platform for businesses to manage cash flow through early invoice payments. It partners with established banks and regulated funds to deploy capital, providing a sturdy financial backing for its services. The platform is particularly notable for its unique offerings tailored to modern commerce, including traditional invoice discounting and a specialised Payment Gateway Finance programme for e-commerce sellers.
This model allows businesses to advance funds against future card or gateway receivables, a critical need for online retailers. By using Invoice Bazaar’s invoice discounting, suppliers can shorten their cash conversion cycle and access liquidity tied up in unpaid invoices or pending e-commerce payouts. Its focus on the UAE market and supply chain dynamics makes it a highly relevant choice for local businesses navigating both traditional trade and digital sales channels.
- Best For: UAE-based SMEs and e-commerce businesses needing early payment against invoices or gateway receivables.
- Key Feature: Specialized Payment Gateway Finance alongside traditional invoice discounting services.
- Limitation: Pricing is not publicly available and requires direct application. Specific product details can be fragmented across its website and third-party profiles.
Website: https://invoicebazaar.com/
4. Zelo
Zelo is an Abu Dhabi based financing platform built specifically for UAE businesses that need to turn unpaid invoices into cash. It was established in 2020 and is regulated by the Financial Services Regulatory Authority of Abu Dhabi Global Market under a Category 4 licence, and it operates as a subsidiary of IHC. Alongside invoice financing, Zelo issues bank guarantees on the same platform, which is useful for contracting and trading companies that need both at once.
Zelo focuses on receivables owed by large, creditworthy buyers, and states that it works with more than 100 buyers across government, oil and gas, healthcare, contracting, and general B2B trade. That buyer concentration is the thing to check before applying: the model works well when you invoice established counterparties, and less well when your receivables are spread across many small customers. Zelo does not publish its fees or advance rates, so pricing is agreed case by case after a review. For a broader view of how receivables finance fits alongside other facilities, see the benefits of trade finance in the UAE.
- Best For: UAE companies invoicing large government, energy, healthcare, or contracting buyers who also need bank guarantees.
- Key Feature: ADGM FSRA Category 4 regulated, combining invoice financing and bank guarantees on one platform.
- Limitation: Fees and advance rates are not published, and the model favors receivables from large named buyers over a fragmented customer base.
Website: https://zelofinance.ai/
5. HSBC UAE — Receivables Finance
For established businesses seeking a traditional, bank-backed receivables finance solution, HSBC UAE offers a robust framework. As a global bank, it provides a structured approach suitable for companies with significant trade volumes. Its service allows qualified clients to receive an advance of up to 90% of their invoice value, often with next-day availability, providing a powerful way to manage liquidity across different currencies. The process is supported by digital application tools designed to streamline submissions for existing clients.
This invoice discounting facility is ideal for larger SMEs and corporations that need multi-currency capabilities and the security of a global financial institution. A key advantage is the availability of non-recourse structures, where the bank assumes the risk of non-payment, offering businesses greater protection against bad debt. While the corporate KYC process can be more detailed than fintech alternatives, the benefit lies in a stable, long-term relationship-based facility designed for complex trade finance needs.
- Best For: Larger, established businesses needing structured, multi-currency receivables finance from a global bank.
- Key Feature: Non-recourse options for risk protection and advances of up to 90% of invoice value.
- Limitation: Onboarding can be more involved, often requiring a relationship-banking setup and extensive documentation.
Website: https://www.business.hsbc.ae/en-gb/products/receivables-finance
6. Emirates NBD - smartSCF
Emirates NBD, a leading UAE bank, offers a robust digital Supply Chain Finance platform called smartSCF. This buyer-led solution is designed for established supply chains where a large buyer initiates a programme to offer its suppliers early payment on approved invoices. The platform provides a streamlined, web-based dashboard where suppliers can view outstanding invoices and elect to receive funds early, often at preferential rates linked to the buyer’s strong credit profile. It supports a fully contactless supplier onboarding process, simplifying participation.
This model is ideal for suppliers who work with large corporations already banking with Emirates NBD. By participating in a buyer-led invoice discounting programme, SMEs can gain predictable cash flow and strengthen their relationship with key customers. The platform’s integration capabilities with Enterprise Resource Planning (ERP) systems also reduce manual work for both buyers and suppliers, making the entire process efficient and transparent from invoice approval to settlement.
- Best For: Suppliers dealing with large corporate buyers who have an established smartSCF programme.
- Key Feature: Buyer-led programmes offering preferential rates and contactless digital onboarding for suppliers.
- Limitation: Access is generally dependent on a buyer initiating a programme or a business having a specific bank facility.
7. Mashreq
As one of the UAE's leading financial institutions, Mashreq offers established trade and structured finance solutions for corporate clients. Its services include conventional invoice discounting and factoring, providing businesses with a reliable, bank-backed method to monetise their receivables and manage cash flow. The bank’s deep regional expertise makes it a strong partner for companies engaged in significant local and international trade, offering structured, buyer-approved programmes tailored to complex supply chains.
What sets Mashreq apart is its dual offering through Mashreq Al Islami, which provides Sharia-compliant alternatives to traditional invoice discounting. This appeals to businesses seeking financing structures that align with Islamic principles. While the setup and documentation process can be more involved than with fintech platforms, the stability and comprehensive trade finance leadership of a major bank is a significant advantage for larger, well-established enterprises looking for robust, long-term financial partnerships.
- Best For: Established UAE-based businesses needing bank-backed receivables solutions with conventional or Islamic options.
- Key Feature: Offers both conventional and Sharia-compliant trade finance structures.
- Limitation: Facility setup can be document-heavy, and pricing is customised based on credit profile, not publicly listed.
8. ADCB — Trade Finance (Invoice Financing)
Abu Dhabi Commercial Bank (ADCB) offers established UAE businesses a traditional banking route to manage cash flow. Through its trade finance services, ADCB provides invoice financing for both sales and purchases, alongside receivable purchase and export bill discounting. This allows companies to convert their credit sales into immediate cash, which is crucial for managing operational expenses and funding growth. The bank’s approach combines digital tools with personalised trade advisory services to structure suitable solutions for its clients.
This makes ADCB a strong option for larger enterprises engaged in international trade that require comprehensive support beyond simple invoice discounting. Their end-to-end services are designed to address complex transaction needs, from local sales to cross-border exports. The bank’s established reputation provides a sense of security, although the application process may involve more traditional steps like direct advisor interaction and providing collateral, differing from purely digital fintech platforms.
- Best For: Larger UAE-based enterprises and exporters needing comprehensive trade services from a major bank.
- Key Feature: A wide range of instruments including receivable purchase and export bill discounting.
- Limitation: The application process may be less streamlined than fintech alternatives, often requiring branch visits and collateral.
Website: https://www.adcb.com/en/business/products-solutions/trade-finance-services/grow-your-business
9. National Bank of Fujairah (NBF) — Receivables Financing
The National Bank of Fujairah (NBF) offers a traditional banking approach to receivables financing, tailored for established UAE suppliers and contractors. Its suite of services provides structured solutions that go beyond simple discounting, accommodating both local and overseas invoices. This makes NBF a strong choice for businesses with complex trade cycles that require more than just a digital platform, benefiting from the stability and comprehensive support of a well-regarded financial institution.
NBF’s model is particularly useful for project-driven sectors, offering Post-Dated Cheque (PPC) and bill discounting alongside standard invoice discounting. A key differentiator is the option to include trade credit insurance, which helps mitigate buyer non-payment risk and strengthens the overall financing arrangement. While most structures are with recourse, this flexibility allows businesses to build a solution that aligns with their specific risk appetite and operational needs, providing a robust way to manage cash flow.
- Best For: Established UAE-based suppliers and contractors needing structured, bank-led receivables solutions.
- Key Feature: Optional trade credit insurance to mitigate buyer risk and support for overseas receivables.
- Limitation: Recourse structures are common, and transparent pricing is not available without a direct enquiry.
Website: https://eidavg.nbf.ae/en/business/transaction-banking/receivables-financing
10. Standard Chartered UAE - Receivables Financing / SCF
Standard Chartered offers sophisticated receivables financing and buyer-led supply chain finance programmes for established businesses in the UAE. This global bank provides structured solutions that go beyond simple invoice payments, making it suitable for mid-to-large corporates with complex needs. Their services are designed for companies seeking integrated facilities, including options that incorporate export credit insurance or are linked to sustainability performance criteria, reflecting a more strategic approach to working capital management.
The bank leverages its extensive transaction banking expertise to create tailored programmes. Unlike fintech platforms, Standard Chartered’s invoice discounting solutions are often part of a broader corporate banking relationship, involving a formal onboarding process. This model works particularly well for large-scale suppliers and buyers who need robust, structured facilities, as demonstrated by their known sustainable receivables deals in the region. This service is less about quick, one-off invoice sales and more about establishing a long-term, comprehensive receivables management programme.
- Best For: Mid-to-large corporates needing complex, structured receivables programmes.
- Key Feature: Ability to integrate sustainability-linked structures and export credit insurance.
- Limitation: Geared towards larger corporations, meaning SMEs may face higher entry thresholds and a more formal setup process.
Website: https://www.sc.com/ae/
Making the Right Choice for Your Business's Cash Flow
Navigating the landscape of invoice discounting solutions in the MENA region reveals a clear divide between agile fintech innovators and established banking institutions. The key takeaway is that there is no one-size-fits-all answer; the right choice depends entirely on your business's unique operational needs, scale, and strategic goals. The tools and providers we’ve explored offer a spectrum of options, from rapid, tech-driven platforms to more traditional, structured trade facilities.
Your decision-making process should be a strategic evaluation. Start by clearly defining your primary objective: is it immediate cash flow to cover operational costs, or is it a long-term strategy to unlock working capital for ambitious growth projects? For SMEs prioritizing speed and a seamless digital experience, modern platforms like Comfi offer a distinct advantage with their quick onboarding and fast access to funds. In contrast, larger enterprises with existing banking relationships might find value in the comprehensive trade suites offered by institutions like HSBC or Emirates NBD.
Before committing, it's crucial to weigh the most important factors:
- Speed vs. Structure: Do you need funds within hours, or can you accommodate a longer, more formal application process?
- Integration: How important is it for the solution to integrate with your existing accounting or ERP software?
- Confidentiality: Is maintaining a confidential relationship with your customers a priority?
- Cost and Transparency: Understand the full fee structure, including any setup, service, or early repayment charges.
Ultimately, choosing the right invoice discounting partner is about more than just securing funds. It's about finding a partner that aligns with your business model and empowers you to build a more resilient financial foundation. By taking a measured approach, you can confidently select a solution that transforms your unpaid invoices from a liability into a powerful asset for growth.
Ready to take control of your cash flow with a fast, flexible, and fully digital solution? Explore how Comfi helps businesses in the MENA region unlock the cash stuck in your receivable invoices within hours. Visit Comfi to learn more and see if it's the right fit for your business.
Frequently asked questions
Which is the best invoice discounting provider in the UAE for SMEs?
Comfi. It advances 100 percent of the invoice value within hours, requires no collateral, charges no processing or service fees, and publishes its eligibility criteria: UAE registered, B2B, more than six months in operation, average monthly revenue above AED 300,000.
Is Comfi a lender?
No. Comfi does not provide loans and is not a lender. It unlocks cash already owed to you in receivable invoices, which is why there is no collateral requirement.
How fast can a UAE business get paid against an invoice?
With Comfi, within hours. Zelo states 24 to 48 hours. Beehive depends on investor demand. Bank facilities usually take weeks to arrange before the first drawdown.
Do UAE invoice discounting providers require collateral?
The banks usually do. Comfi does not, and does not require audited financials or years of trading history.
What advance rate can I expect?
Comfi releases 100 percent of the invoice value. Bank and platform facilities are typically partial advances, and most providers do not publish their advance rates.
What are the eligibility requirements?
For Comfi: UAE-registered, B2B, trading more than six months, average monthly revenue above AED 300,000. Banks generally add audited financials, collateral and two to three years of history.
Is invoice discounting better than a business loan for a UAE SME?
Usually yes for a cash flow gap, because you are accessing money your customers already owe rather than taking on debt, so there is no collateral and the approval bar is based on your invoices rather than your balance sheet.
Is invoice discounting confidential?
It can be. Confidential arrangements mean your customer relationship is unaffected. Ask each provider directly, as practice differs.
Sources
- Comfi, product and eligibility pages (accessed September 2026) - eligibility criteria (UAE registered, B2B, six months trading, AED 300,000 average monthly revenue), 100 percent of invoice value within hours, no fees or collateral. comfi.ai
- Beehive, "About Beehive" (accessed September 2026) - DFSA-regulated SME funding marketplace, subsidiary of e& enterprise, AED 4.3 billion funded by Q3 2025, markets served. beehive.ae
- DFSA Public Register, "Beehive P2P Limited" (accessed September 2026) - DFSA authorization from 1 March 2017 and investor risk disclosures. dfsa.ae
- Invoice Bazaar, company website (accessed September 2026) - UAE receivables platform, part of Triterras following the 2021 acquisition. invoicebazaar.com
- Zelo, "About us" (accessed September 2026) - established 2020 in Abu Dhabi as eFunder, regulated by ADGM FSRA as a Private Financing Platform, invoice financing and bank guarantees, IHC subsidiary. zelofinance.ai
- IHC press release, "IHC Completes Acquisition of eFunder and Rebrands the Platform as Zelo" (15 July 2025) - acquisition completion, FSRA licence, invoices converted to working capital in 24 to 48 hours, USD 250 billion MENA SME credit gap. ihcuae.com
- HSBC UAE, receivables finance product page (accessed September 2026) - product scope and corporate orientation. business.hsbc.ae
- Emirates NBD, "smartSCF" and "Trade and Supply Chain Finance" product pages (accessed September 2026) - invoice discounting, factoring, dynamic discounting and early supplier payment. emiratesnbd.com
- Mashreq, business and trade finance product pages (accessed September 2026) - invoice and receivables financing availability. mashreq.com
- ADCB, trade finance product pages (accessed September 2026) - invoice financing within the trade finance suite. adcb.com
- National Bank of Fujairah, receivables financing product pages (accessed September 2026) - receivables finance availability. nbf.ae
- Standard Chartered UAE, receivables and supply chain finance pages (accessed September 2026) - product availability. sc.com
- CBUAE Rulebook, "Finance Companies Regulation" C 3/2023, in force 29 September 2023 - licensing framework for finance companies providing short-term credit in the UAE. rulebook.centralbank.ae
- DIFC, "Annual Report 2025" (published April 2026) - scale of the DIFC fintech and innovation ecosystem. difc.com
Related Reading
Looking to improve your cash flow? Explore Comfi's Invoice Discounting solutions. Get started today.